Fixed Index Annuity Explained
By Hans Goldstein, founder, Retirement Literacy Foundation · Updated
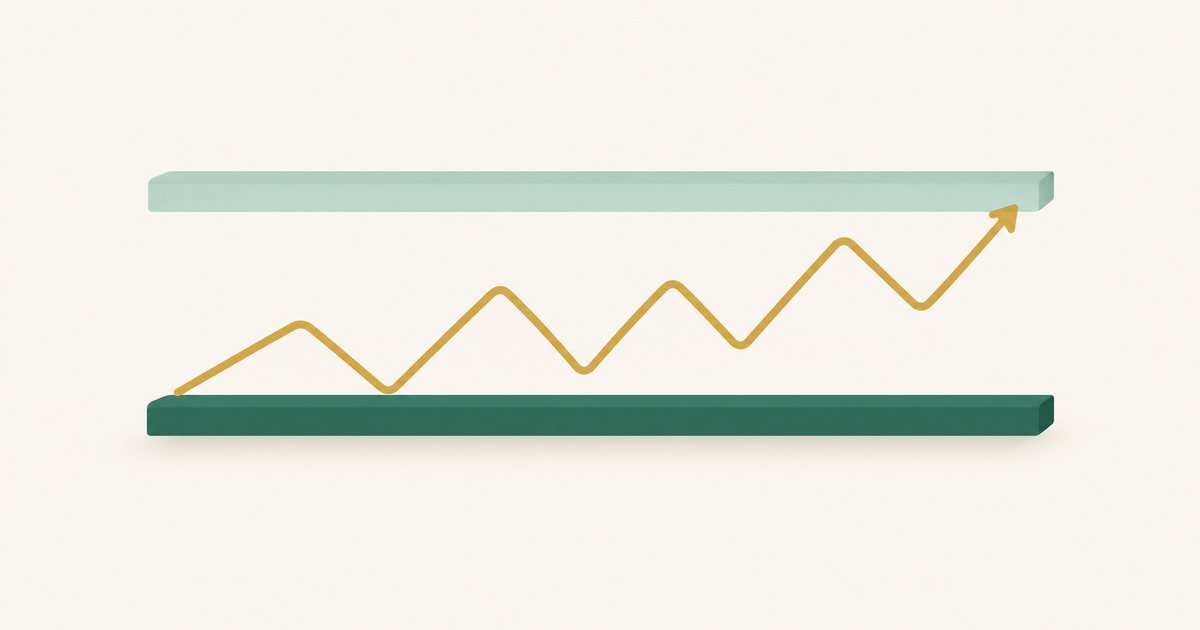
How the crediting works
- Cap: the most you can be credited in a period. With a 9% cap and an index gain of 15%, you get 9%.
- Participation rate: the share of the index gain you get. At 60% participation and a 10% gain, you get 6%.
- Spread: a percentage subtracted from the gain. With a 3% spread and an 8% gain, you get 5%.
- Floor: usually 0%, so a falling index credits nothing rather than a loss.
- Index returns usually exclude dividends, and crediting is commonly measured once a year (point to point).
What the insurer can change
Caps, participation rates and spreads are typically guaranteed only for the first term, often one year. After that the insurer can reset them, down to the minimums written into the contract. The RLF counted those minimums across 99 contracts and found that most allow a cap as low as 1%: see the FIA minimum caps study.
Costs and features
- Surrender charges commonly last 7 to 10 years or more. See surrender charges.
- Riders, such as income or enhanced death benefit riders, often carry a yearly charge. See living benefit riders.
- Commission: indexed annuities paid the highest published average commission among fixed annuities. See annuity commissions.
- Bonuses are sometimes offered, usually paired with longer surrender periods or lower caps.
Taxes
Credited interest grows tax-deferred and is taxed as ordinary income when withdrawn, even though it is linked to a stock index. See how annuities are taxed.
Common questions
Can you lose money in a fixed index annuity?
The credited value does not fall because of index losses, but surrender charges, market value adjustments and rider fees can reduce what you receive, especially if you leave early.
Is a fixed index annuity a security?
Generally no. Fixed index annuities are regulated as insurance products by state insurance departments. Variable annuities are securities.
Are fixed index annuity caps guaranteed?
Usually only for the first term. After that the insurer can lower them down to the contract's guaranteed minimum.
Related
- FIA minimum caps study
- Annuity types, pros and cons
- Living benefit riders
- Surrender charges
- All annuity education pages
More on annuities: How Do Annuities Work? A Plain-English Guide · How Are Annuities Taxed? · Inherited Annuity Taxes · 1035 Exchange · Annuities in an IRA · Annuity Surrender Charges and How to Get Out of an Annuity · Types of Annuities and Their Pros and Cons · What Is a MYGA? Multi-Year Guaranteed Annuities Explained · Immediate Annuity (SPIA) Explained · Variable Annuity Explained · Annuity vs CD
Education only; nothing is sold here and no product is recommended. Hans Goldstein, founder of the Retirement Literacy Foundation, is also a licensed California insurance producer (#4273294). Tax rules depend on your situation; check with a tax professional before acting.